Building businesses on the internet is not necessarily the money-burning exercise that many have found it to be, if this morning’s financial results from Pearson are anything to go by. Having spent a huge sum on Net investment this year, the company not only turned in profit higher than expected but also reported that its FT Internet business will stop losing money next year.
The company posted pre-tax profits of £333 million for the year to 31 December 2000. Whilst this is 17% lower than the £402 million of last year, it is still ahead of analysts’ expectations. The fall in profits comes after a heavy investment of £196 million in the internet.
Pearson says the results show record performance with sales up 16% and operating profits up 17% to £686 million (pre-internet expenditure). The FT Group, which includes the Financial Times newspaper, turned in a profits rise of 41%. Perhaps most encouragingly given the money-consuming nature of a lot of online business, FT Internet enterprises is on track to break even by end of 2002, according to Pearson.
During 2000 the company also merged its Pearson TV operation with European broadcaster CLT-Ufa and at the same time took a 22% share in RTL Group, Europe’s largest television company.
Marjorie Scardino, Pearson’s chief executive, says: “This is another great set of results. For the fourth straight year, we increased our organic revenue growth, improved our margins and turned in a good cash performance. All the time, we are making the moves that enable Pearson to grow more quickly and more profitably.”
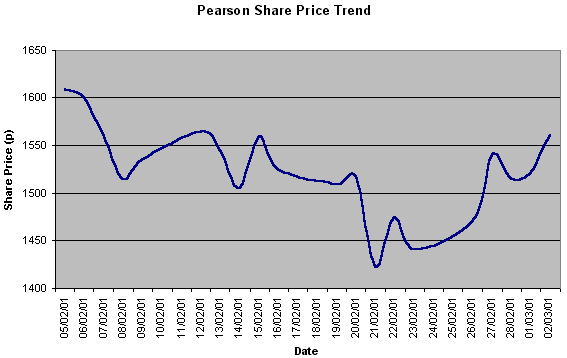
Pearson shares shot up at the positive news early this morning, only to fall back across the course of the morning. By midday stock was down 36p at 1,525p. Brokers’ reactions were mixed. ABN Amro has taken a Reduce stance because stock is priced at 17 times earnings – a little ‘stretched’ in the broker’s opinion; UBS Warburg and WestLB Panmure reckon Hold and Credit Lyonnais gives an Add rating.
ABN Amro: Reduce WestLB Panmure: Hold UBS Warburg: Hold Credit Lyonnais: Add