
Fourteen years of gradual consolidation of the ITV Network this morning came to fruition, with the long-awaited merger of Carlton and Granada to create a single ITV company worth more than £5 billion.
ITV plc made its first appearance on the Stock Exchange today with a share price of 143½p. Shares in Carlton and Granada were delisted at the end of trading on Friday after the deal received the final go-ahead from the High Court.
For ITV, this represents something of a fresh start. Regulatory changes, under the recent Communications Act, have allowed ITV to create a leaner structure, with lower costs and a more focused approach. This could prove to be a much-needed shot in the arm for the broadcaster.
It is expected that the merged company will benefit from cost savings of around £100 million. It could even be higher than this, according to some analysts. Merrill Lynch believes that even greater synergies could be found if ITV were to buy up the remaining five ITV licensees (Channel, GMTV, ITN, SMG and Ulster Television). However, such acquisitions would be subject to further competition scrutiny by the regulators.
Further savings may come from a reduction in the fee ITV pays for its licence, if Ofcom decides to renew the terms for ITV franchises from January 2005. This could lead to a fall in licence fess of as much as 60%, although Merrill Lynch analysts are modelling for a 40% cut.
Ofcom is also due to review broadcasters’ public service broadcasting (PSB) obligations this year and there is a possibility that ITV’s requirements in this area may be relaxed. Currently ITV spends around £250 million a year on regulatory requirements and PSB commitments. Merrill Lynch estimates that PSB changes may save ITV in the region of £25-£75 million, although this has not been factored in to the broker’s forecasts.
The contract rights renewal system (CRR) – which links what ITV can charge advertisers with market share and audiences – is also likely to have some effect on revenue growth. Over the last decade, ITV’s advertising share has declined by 31%, but its share of commercial impacts is 38% lower, largely as a result of the falling audience share. It is anticipated that the CRR will go some way to balancing this discrepancy.
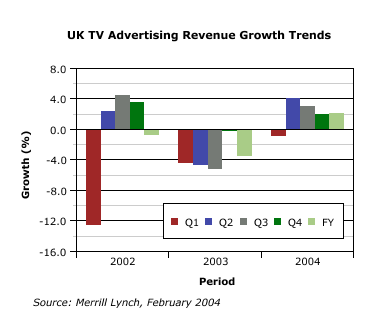
Advertising revenue Merrill Lynch is forecasting a full-year advertising revenue growth of 2.1% for ITV1, with trading picking up after a slightly negative Q1. The second quarter will benefit from the European Championships, although the Olympics in Q3 will have little effect as they are being broadcast on the BBC.
| ITV1 Quarterly Advertising Revenues | ||||||
| Q1 | Q2 | Q3 | Q4 | FY | ||
| 2002 | Revenue (£m) | 388 | 433 | 392 | 475 | 1,687 |
| Growth (%) | -12.6 | 2.3 | 4.4 | 3.6 | -0.8 | |
| 2003 | Revenue (£m) | 371 | 413 | 372 | 474 | 1,628 |
| Growth (%) | -4.4 | -4.7 | -5.2 | -0.2 | -3.5 | |
| 2004 | Revenue (£m) | 367 | 429 | 383 | 483 | 1,662 |
| Growth (%) | -0.9 | 4.0 | 3.0 | 2.0 | 2.1 | |
| Source: Merrill Lynch, January 2004 | ||||||
ITV3 launch The creation of a single ITV will be marked with the launch of its third mainstream channel, ITV3, by the end of the this year. The company’s chief executive, Charles Allen, claims that ITV3 will be aimed at older, upmarket viewers with an appetite for drama. It has yet to be decided whether ITV3 will be a free-to-air or subscription channel.
ITV is planning to create other new channels and the next most likely project is a station aimed specifically at children.
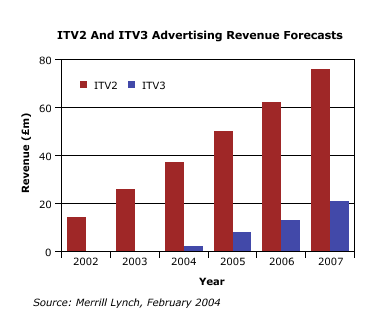
The table below shows Merrill Lynch’s forecasts for advertising revenues at ITV1, ITV2 and ITV3 over the next three years.
| ITV Advertising Revenue Breakdown Forecasts | ||||||
| 2002 | 2003 | 2004 | 2005 | 2006 | 2007 | |
| ITV1 | 1,686 | 1,628 | 1,662 | 1,717 | 1,770 | 1,827 |
| ITV2 | 14 | 26 | 37 | 50 | 62 | 76 |
| ITV3 | 0 | 0 | 2 | 8 | 13 | 21 |
| Source: Merrill Lynch, February 2004 | ||||||
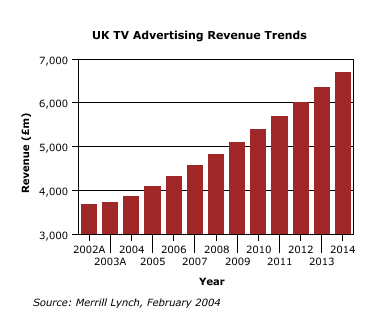
Long-term TV revenues In the longer-term the broker forecasts that there will be a compound annual growth rate (CAGR) for television ad revenues of 5.5% between 2004 and 2014. This model assumes that TV’s share of advertising will remain pretty much consistent throughout the period and that there will be an economic cycle of around eleven years in length.
Over the same period, ITV1’s advertising CAGR is forecast to be 3.2%.
| Long-Term UK Advertising Forecasts | |||||||||||||
| 2002A | 2003A | 2004 | 2005 | 2006 | 2007 | 2008 | 2009 | 2010 | 2011 | 2012 | 2013 | 2014 | |
| Total advertising (£m) | 13,064 | 13,195 | 13,590 | 14,379 | 15,209 | 16,082 | 17,001 | 17,967 | 18,984 | 20,053 | 21,177 | 22,359 | 23,602 |
| Growth (%) | 0.4 | 1 | 3 | 5.8 | 5.8 | 5.7 | 5.7 | 5.7 | 5.7 | 5.6 | 5.6 | 5.6 | 5.6 |
| Television advertising (£m) | 3,677 | 3,725 | 3,863 | 4,087 | 4,323 | 4,571 | 4,832 | 5,106 | 5,395 | 5,699 | 6,019 | 6,355 | 6,708 |
| Growth (%) | 4.3 | 1.3 | 3.7 | 5.8 | 5.8 | 5.7 | 5.7 | 5.7 | 5.7 | 5.6 | 5.6 | 5.6 | 5.6 |
| Source: Merrill Lynch, February 2004 | |||||||||||||